Carlos Slim’s Grupo Carso is stitching together something Mexico’s private oil patch hasn’t seen before: a Mexican-controlled operator with a producing offshore block. A $270 million agreement to buy Lukoil’s Mexico unit would give Carso full control of the Ichalkil and Pokoch fields off Campeche—along with a chunky debt tab and a thicket of regulators on both sides of the border. The barrels aren’t massive today, but the move hints at a bigger energy play that’s been building in plain sight.
A deal that flips the script in Mexico’s upstream
Grupo Carso has agreed to purchase Lukoil’s stake tied to the Ichalkil–Pokoch development, a producing offshore project in the Gulf of Mexico. The transaction is being executed through Zamajal, Carso’s energy vehicle, and it would place a Mexican conglomerate in a role usually occupied by foreign operators since Mexico reopened its upstream sector to private participation a decade ago.
In practical terms, the deal is less about a single press-release headline and more about control. Once the conditions are met, Carso would not only hold the economic interest in the fields but also sit in the driver’s seat operationally. That operator status matters in Mexico, where the right to run a block carries responsibility for work programs, budgets, field development decisions, and the sometimes messy reality of keeping barrels flowing.
What Carso is buying and what it is taking on
The purchase centers on Fieldwood Mexico, the entity that holds an interest in the contract area that includes the Ichalkil and Pokoch fields. The agreed price is $270 million for the equity, and Carso would also assume obligations linked to the asset, including a $330 million debt balance owed to Lukoil. Put together, the financial exposure is closer to the kind of number that gets board-level attention, not a side bet.
This isn’t Carso’s first move into these fields. The company already secured the other 50% interest through a prior acquisition in 2024. The Lukoil-linked stake is the missing half that turns a significant position into full control. If the closing happens as planned, Carso would effectively consolidate the project under one corporate umbrella, simplifying decisions that, until now, had to be negotiated across partners with different priorities.
The fine print is just as important as the headline. Closing is subject to multiple approvals in Mexico, and the transaction also requires specific authorization from the U.S. Treasury’s Office of Foreign Assets Control due to sanctions imposed on Lukoil. That adds a geopolitical layer to what would otherwise appear to be a straightforward corporate consolidation.
The fields behind the name and the numbers that matter
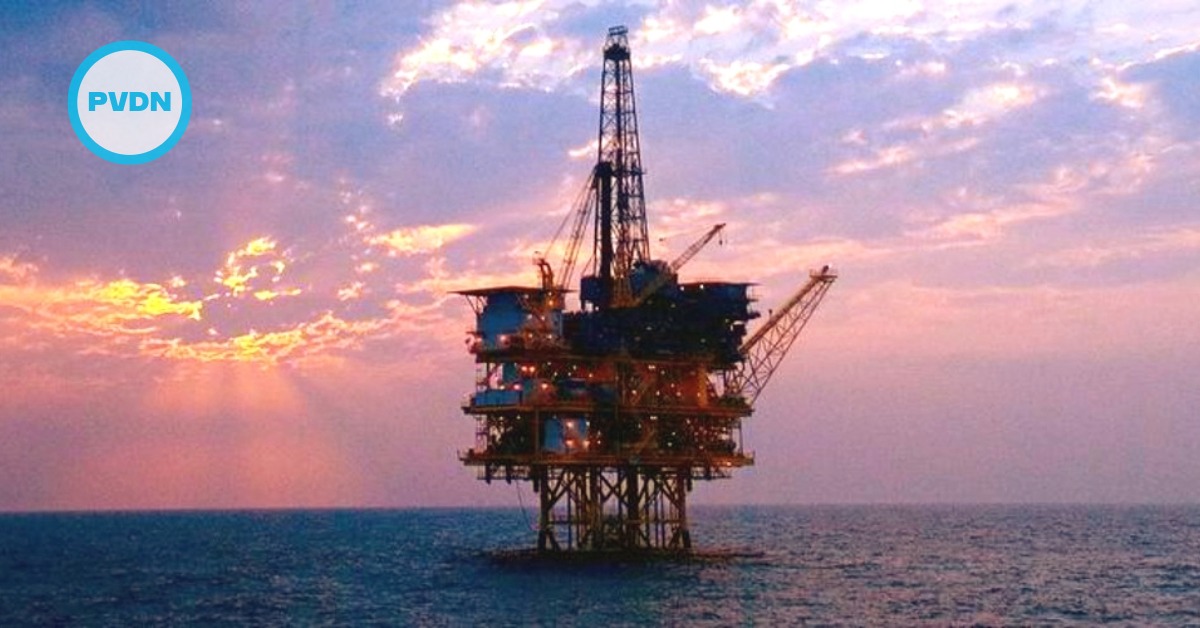
Ichalkil and Pokoch sit off the coast of Campeche in shallow waters, part of the producing zone that has long anchored Mexico’s offshore output. Production began in late 2021, and the asset has moved through development phases that reflect the typical arc of offshore projects: early ramp-up, optimization, and ongoing drilling to sustain or lift output.
Publicly available figures show the project producing in the high single-digit to low double-digit thousands of barrels per day in recent reporting, with associated natural gas output also disclosed in some summaries. One reason the numbers can feel slippery is that official, centralized reporting on private operators’ production has become less transparent, leaving investors and the public to rely more on corporate filings and deal disclosures.
Reserves are where the story gets more nuanced. Recent reserve disclosures tied to the project cite proved and probable volumes of light oil in the tens of millions of barrels and gas in the tens of billions of cubic feet. Earlier, when the Russian company entered the project, the resource narrative was far more ambitious, describing recoverable hydrocarbons in the hundreds of millions of barrels of oil equivalent and a multi-phase plan with a much higher peak rate. Both can be true at once because they describe different things: what the fields might hold and deliver over their life versus what is booked under stricter reserve definitions at a given moment.
Carso’s own investor language suggests it sees meaningful upside. In a recent quarterly report, the company said it expected production from its participation in Ichalkil and Pokoch to exceed 25,000 barrels per day of crude-equivalent in the following year. That kind of statement is a tell: the asset is being managed as a growth platform, not a legacy holding to milk and exit.
The sanctions wrinkle and the regulators’ checklist
The timing of this deal is not accidental. Lukoil was sanctioned by the U.S. Treasury in October 2025 as part of broader measures aimed at Russia’s energy sector. Since many cross-border oil transactions touch the dollar system, OFAC clearance becomes a gating item, even when the asset being sold sits in Mexico and the buyer is Mexican.
Mexico’s side of the approval process is also material. A transaction that consolidates control over an offshore producing asset can trigger scrutiny from energy authorities and competition regulators, especially when it changes who operates and how obligations are funded and executed. The approvals process can be routine, but it is rarely fast and is often sensitive to political optics in an industry closely tied to national identity.
How this fits Slim’s broader energy push
Taken alone, Ichalkil–Pokoch is a notable producing project. Taken alongside Carso’s other moves, it looks like a strategy.
Over the past few years, Slim’s businesses have been building exposure across the energy value chain, mixing upstream participation with service contracts that plug directly into Pemex’s needs. Carso has also positioned itself around gas, including offshore ambitions that align with Mexico’s recurring challenge: securing a reliable natural gas supply while domestic production struggles to keep pace with demand and infrastructure constraints.
For readers living in Mexico, that matters less as an oil-industry chess match and more as a signal about where large private capital believes it can still operate. Whether you follow energy closely or only notice it when electricity reliability becomes dinner-table conversation, the underlying point is the same: a heavyweight local conglomerate is betting that Mexico’s energy sector will continue to make room—formally or informally—for private participation that complements, rather than replaces, Pemex.
What it means for Mexico’s private operators and for the rest of us
Calling Carso “the biggest private oil operator” depends on how you define the field. By production, some foreign-led operators have been larger in recent publicly available snapshots. What changes here is the identity of the operator and the fact that the operating company would be Mexican-controlled, with full alignment between ownership and decision-making.
That has two immediate implications. First, it could make the project more nimble: fewer partner negotiations, clearer funding decisions, and a single strategic direction. Second, it could make the project more politically resilient, because a Mexican operator with a track record of working with Pemex may find it easier to navigate policy shifts than a foreign player reading the room from afar.
For expats, the day-to-day impact is indirect, but not imaginary. Mexico’s fiscal health, infrastructure investment, and even the tone of national economic debate are shaped by oil revenues, Pemex’s balance sheet, and the success or failure of projects that keep production steady. A deal like this is one more indicator that the country’s energy future will likely be hybrid: Pemex at the center, private capital at the edges, and a handful of domestic giants trying to prove they can do more than just supply the shovels.
With information from El Economista, El País, Bolsa Mexicana de Valores (Eventos Relevantes GCARSO), Grupo Carso Reporte 3er Trimestre 2025 (PDF), U.S. Treasury press release on Russia-related sanctions, OFAC recent actions on Russia-related designations, Reuters background on Lukoil’s Area 4 entry (Feb. 25, 2022)