For years, China’s role in Latin America was easy to summarize—buy the region’s raw materials, sell back finished goods. That story is still true, but it’s no longer the whole picture. With trade near $518 billion in 2024 and a rising stock of investment, Beijing’s footprint now runs through ports, power projects, mines, and—quietly—factories that feed North American supply chains. Mexico sits at the crossroads, pulled by nearshoring and pushed by new tariff politics. Here’s what’s changing, and why it matters.
A relationship built on volume
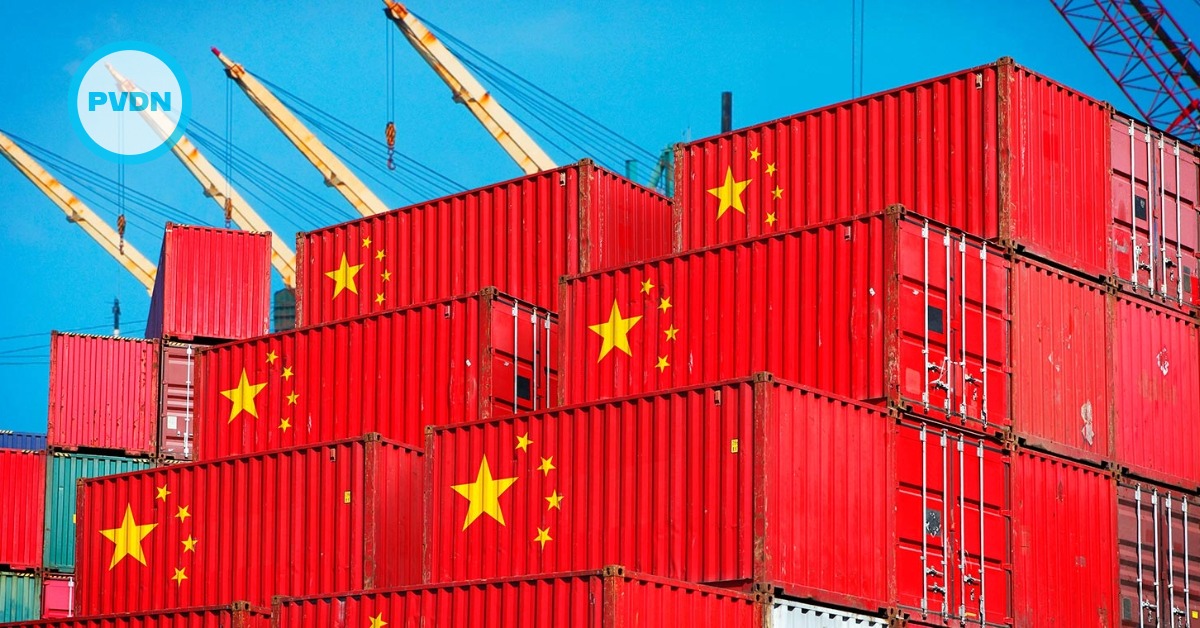
In just a couple of decades, China moved from the margins of Latin American commerce to its center. Total goods trade between China and the region climbed to roughly $518 billion in 2024, a level that would have sounded implausible at the start of the 2000s. The scale matters because it changes the daily incentives of governments and businesses: once trade reaches that size, it stops being a “foreign policy” topic and starts showing up in budgets, ports, trucking corridors, factory planning, and consumer prices.
The pattern of exchange still has a familiar shape. Latin America largely sells what the region is rich in—minerals and metals, soy and other agricultural commodities, and energy products—while China sells what it excels at producing at scale, from machinery and electrical equipment to vehicles and components. That imbalance has real consequences. Commodity booms can lift export revenues quickly, but they also leave countries exposed when prices fall. And when a market as large as China becomes the main destination for certain exports, domestic politics can begin to orbit around access to that market.
This is why China’s position differs across the map. In much of South America, China is already the top trading partner. Across the wider region, it typically sits just behind the United States. Either way, the old assumption that Latin America’s external economy is automatically U.S.-centered no longer fits the data.
Investment is deepening the footprint
Trade explains the headlines, but investment explains the staying power. Estimates of China’s accumulated direct investment position in Latin America now sit just under $190 billion. A large share of that stock is tied to energy, mining, and natural resources—sectors that anchor long-term presence because projects are capital-heavy, politically sensitive, and hard to unwind.
What’s changing is where the new emphasis is going. The focus isn’t only on digging minerals out of the ground; it’s also on moving goods and energy faster and more reliably. Ports, terminals, logistics corridors, electricity generation, and grid infrastructure are the kinds of assets that quietly shape how a region trades for decades. Peru’s Chancay mega-port is often cited as a symbol of this shift: it shortens routes across the Pacific and strengthens the physical link between South American exports and Asian markets.
At the same time, the investment story has matured. Annual flows have not kept rising in a straight line; they’ve eased from earlier peaks, and the mix of deals has diversified. That matters because it suggests a move away from a single era defined by mega-projects and big-ticket financing toward a more targeted approach—smaller footprints in more places and greater integration into supply chains that run through the Americas.
Mexico’s nearshoring squeeze
Mexico is the complicated case, and for many expats living here, it’s also the most visible one. On the surface, Mexico’s relationship with China can look paradoxical. Mexico is deeply tied to the U.S. market, and much of its industrial economy is built around North American integration. Yet Chinese goods are everywhere in the Mexican consumer landscape, and Chinese companies are increasingly present in the industrial one.
Start with trade: Mexico’s imports from China have surged over the past decade, and the relationship is heavily one-sided. Mexico exports comparatively little to China, while importing huge volumes of intermediate and finished goods. For manufacturers, that can be a feature rather than a bug—Chinese inputs can be cheaper and easier to source at scale. But for policymakers, it’s a constant tension: imports help factories run, yet they can also squeeze domestic producers and widen the trade deficit.
Then there’s investment. Official numbers show that Chinese direct investment in Mexico remains modest compared with U.S. capital. But Mexico’s role in the supply chain is changing the incentives for Chinese firms. When global companies reconfigure production to serve North America, Mexico becomes an obvious platform—close to U.S. consumers, embedded in regional manufacturing ecosystems, and integrated into cross-border logistics. That’s why the more concrete China story in Mexico often shows up as suppliers—especially in auto parts and electronics—plugging into existing industrial clusters.
This is also where politics enters the factory floor. Mexico began 2026 with a broad set of higher import tariffs targeting products from countries without a free trade agreement with Mexico, a category that includes China. The measure covers a wide range of goods and reflects a balancing act: protecting domestic industries and responding to external pressure to prevent North America from becoming an easy entry point for Asian-made goods, while avoiding undermining the supply chains that keep Mexican factories competitive.
For residents, the push and pull can be felt in subtle ways—what’s available on store shelves, which brands appear on the streets, and how quickly industrial zones expand around logistics hubs. It can also influence job growth in specific corridors, where new suppliers arrive to serve larger plants rather than building consumer-facing brands.
What comes next for the region
Latin America’s challenge is not whether to engage China; the region is already deeply engaged. The harder question is how to shape that engagement so it produces long-term gains rather than short-term dependency. For commodity exporters, that means building more processing and higher-value activity at home, not only shipping raw materials abroad. For governments negotiating infrastructure and energy projects, it means transparency, safeguards, and contracts that keep public interest front and center.
Mexico’s version of the question is even sharper because it sits inside the gravitational pull of two economic giants. The country benefits from nearshoring and regional production, but it also inherits the geopolitical friction that comes with it. In practical terms, Mexico will keep trying to do three things at once: keep its manufacturing engine supplied, protect sensitive industries from being undercut, and avoid becoming the battleground where U.S.-China rivalry turns into industrial whiplash.
The big takeaway is that China’s footprint is no longer a single story about commodities. It’s a layered presence—trade, investment, logistics, technology, and supply-chain strategy—reshaping how Latin America connects to the world. And for Mexico, it’s becoming a daily reality of economic life, not a distant headline.