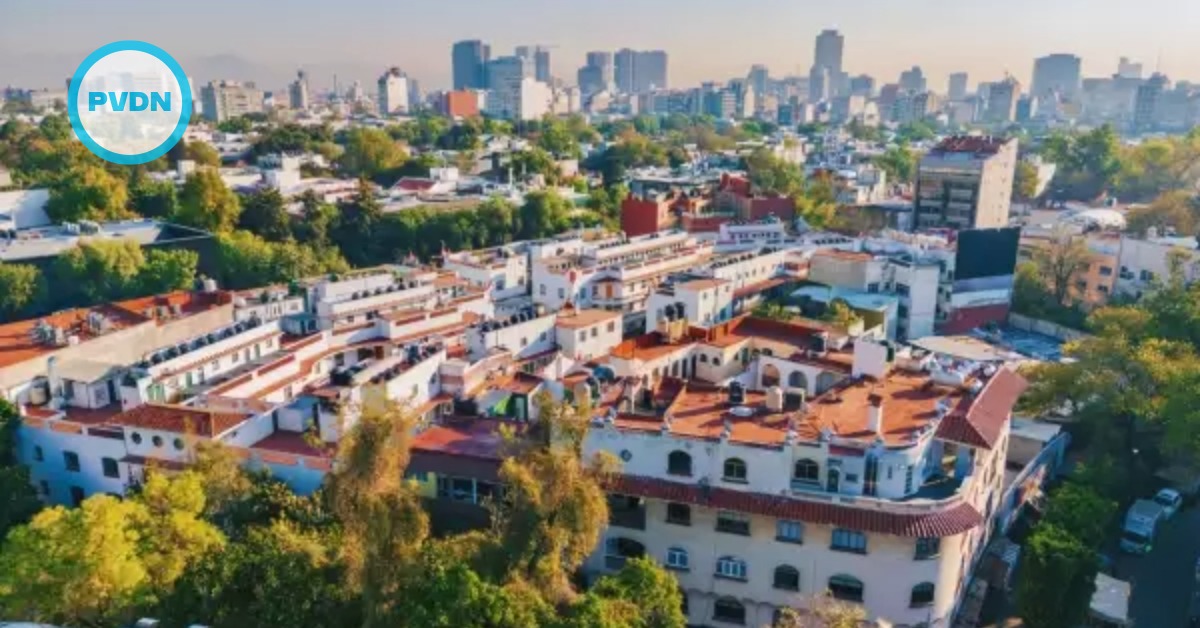
A new fault line is opening in Mexico City’s housing market. It sits below the luxury tier and above subsidized or social housing. This is the space where many working and middle-income households would normally look to buy. In today’s market, that bracket is increasingly difficult to produce.
Recent market data clearly shows the shift. New housing output in the capital has fallen since 2020, and the share of mid-market housing has also dropped. At the same time, the city remains the country’s most expensive market, with a price per square meter. That combination matters. When prices rise, but margins stay thin, developers do not always stop building. They change what they build.
Why the math no longer works
The first problem is land cost. Buildable land in central and well-connected parts of the capital is scarce and expensive. On top of that, not every parcel can be easily converted to housing. That limits the number of sites where a sub-3-million-peso project can work.
The second problem is the construction cost. In an earthquake-prone city, stricter seismic rules are necessary. Few would argue otherwise. But developers and consultants say those rules have also made vertical construction more expensive, with heavier use of steel and concrete in many projects. Safety is non-negotiable. The financial effect is still real.
The third problem is time. Permitting delays can stretch a project timeline by years before sales begin. In a market with moving costs, changing credit conditions, and uncertain demand, that delay becomes part of the price. A project that looks viable on paper can stop looking viable once the carrying costs are added.
Why developers are moving upmarket
When risk rises, many builders move toward higher-end segments. The margin per unit is larger there. That gives developers more room to absorb delays, design changes, and financing pressure. In practical terms, a city that needs more middle-market housing ends up getting more expensive housing instead.
That shift creates its own imbalance. Higher-end inventory can pile up if demand does not keep pace. Meanwhile, the lower and middle ranges remain undersupplied. The city ends up with a market that is active on paper but mismatched in reality. It is producing homes, but not enough of the homes that many households can actually afford.
This matters even for readers who are not planning to buy in Mexico City. A shortage of attainable new units does not stay confined to the sales market. Over time, it feeds pressure into rents, commuting patterns, and neighborhood change. When households cannot buy near work, many rent longer or move farther out. That adds strain to the broader urban system.
This is not only a private-sector story
It would be easy to frame this as a fight between developers and affordability advocates. The reality is more complicated. Housing affordability in Mexico City is being shaped by several forces at once. Construction economics is one part. Interest rates and weaker mortgage demand are other factors. Public policy is another.
City officials have already acknowledged the pressure. Mexico City has expanded its push for affordable and public rental housing, tied housing policy more directly to anti-displacement goals, and promised permit simplification and digitization. The city has also set out broader housing targets during the current administration. That matters because the market alone is not solving the shortage.
Still, public policy will not quickly erase the underlying math. Faster approvals help. More public land helps. Better coordination between zoning, infrastructure, and housing goals helps. But as long as land remains costly and project timelines remain uncertain, sub-3-million-peso housing will stay hard to deliver at scale in the capital.
What comes next
The key question is whether the city can restore predictability to the process without weakening safety rules. The issue is not whether buildings should be safer. They should. The issue is whether the capital can protect residents while still making room for housing that middle-income households can realistically afford.
For now, the trend is moving in the wrong direction. Mexico City continues to need more affordable housing near jobs and services. Yet the private market is being nudged toward higher-priced, wider-margin products. That does not just reshape the skyline. It reshapes who gets to stay in the city, who gets pushed outward, and what kind of housing future the capital is building for itself.