A widening fraud case in Nuevo León has pushed Mexico’s pre-sale housing market toward an uncomfortable question that buyers often face too late. Developers are now weighing insurance- or bond-style safeguards to protect deposits when projects stall or fail. The idea sounds simple. The current rules, the limits of private guarantees, and the cost of shifting risk away from buyers show why the debate is more difficult than the sales pitch suggests.
Developers weigh new protections after pre-sale fraud
Developers are now discussing a stronger safety net for pre-sale housing buyers after the Proyectos 9 case in Nuevo León grew to 288 identified victims and nearly 800 million pesos in claimed losses. The idea under discussion is not another disclosure rule. It is a financial backstop that could return buyer deposits when a project stalls or collapses.
The debate moved quickly because the losses are no longer theoretical. Nuevo León Fiscal General Javier Flores Saldívar said the case had reached “288 victims, with 730 million pesos and 3.7 million dollars” in claimed damage. The figure, he said, put the case near 800 million pesos. Prosecutors have said complaints continue to arrive.
The case has also sharpened scrutiny of a common promise in Mexico’s residential market. In a pre-sale, buyers often invest in a project long before delivery. That can help finance construction and lock in a price, but it also leaves buyers exposed if permits, construction costs, sales, or the developer’s liquidity falters before the building is delivered.
Existing rules leave a gap
Mexico already has a consumer-protection framework for home sales. The federal standards platform lists NOM-247-SE-2021 as current and describes it as covering commercial information, advertising, and minimum contract elements for home sales. It was published in March 2022 and entered into force in September 2022.
The Federal Consumer Protection Law also places specific duties on housing sellers. Article 73 states that contracts for the sale of homes by developers, builders, promoters, and others to the public must be registered with Profeco. Article 73 Bis states that in pre-sales, the seller must provide the full executive construction project, ownership documents, information on liens, and relevant permits or licenses. Article 75 bars providers from receiving payment until the contractual relationship is in writing, except for investigation costs.
Those rules create paperwork, disclosure, and administrative leverage. They do not automatically put an insurer, bank, or bonding company behind every deposit. That gap is where the new debate sits. Current rules can help buyers challenge false advertising, missing permits, or abusive contracts. They are weaker when the core problem is that the project cannot finish, and the developer no longer has the cash to return years of payments.
A bond-style idea enters the debate
One model now being discussed looks to Spain. The country’s old Law 57 of 1968 required developers who received advance payments for homes under construction to guarantee refunds through insurance or a bank guarantee if construction did not start or was not completed within the agreed term. The structure also required that those payments be deposited into a special account tied to the project.
That is a different concept from a project trust alone. A trust can organize money and ownership rights, but it does not always mean a third party will repay buyers if the development fails. A bond-style or insurance-backed model would shift at least part of that repayment risk outside the developer.
Early product shows the limits
A recent Monterrey project shows both the market interest and the limits. Libertad HO introduced a program called Certeza Libertad that includes compensation equal to 10 percent annually on invested capital when delivery is delayed by more than three months. It also includes unemployment coverage of 400,000 pesos and disability or death coverage of up to 6 million pesos backed by AXA.
The delay component, however, is not backed by AXA. It is absorbed directly by the developer, according to information shared about the program. That means the protection still depends on the developer’s ability to keep paying if the project faces deeper financial stress. The program is also limited to a specific stage of the project and does not apply retroactively to earlier buyers.
Community Factory, the developer behind Libertad HO, described the program in a company post as a response to the old pre-sale risk model. “Certeza Libertad is our response,” it said in Spanish, describing the plan as shifting part of the risk that had previously fallen only on the buyer.
That is narrower than the stronger proposal currently under discussion. A third-party guarantee would change the transaction, as the buyer’s claim for repayment would not depend solely on the developer who failed to deliver. The difficult part is pricing that risk. Construction delays can come from permits, financing, labor, material costs, court disputes, slow sales, or broader market shocks. An insurer or bonding company would need to decide which failures are covered, when repayment is triggered, and how much a developer pays for that protection.
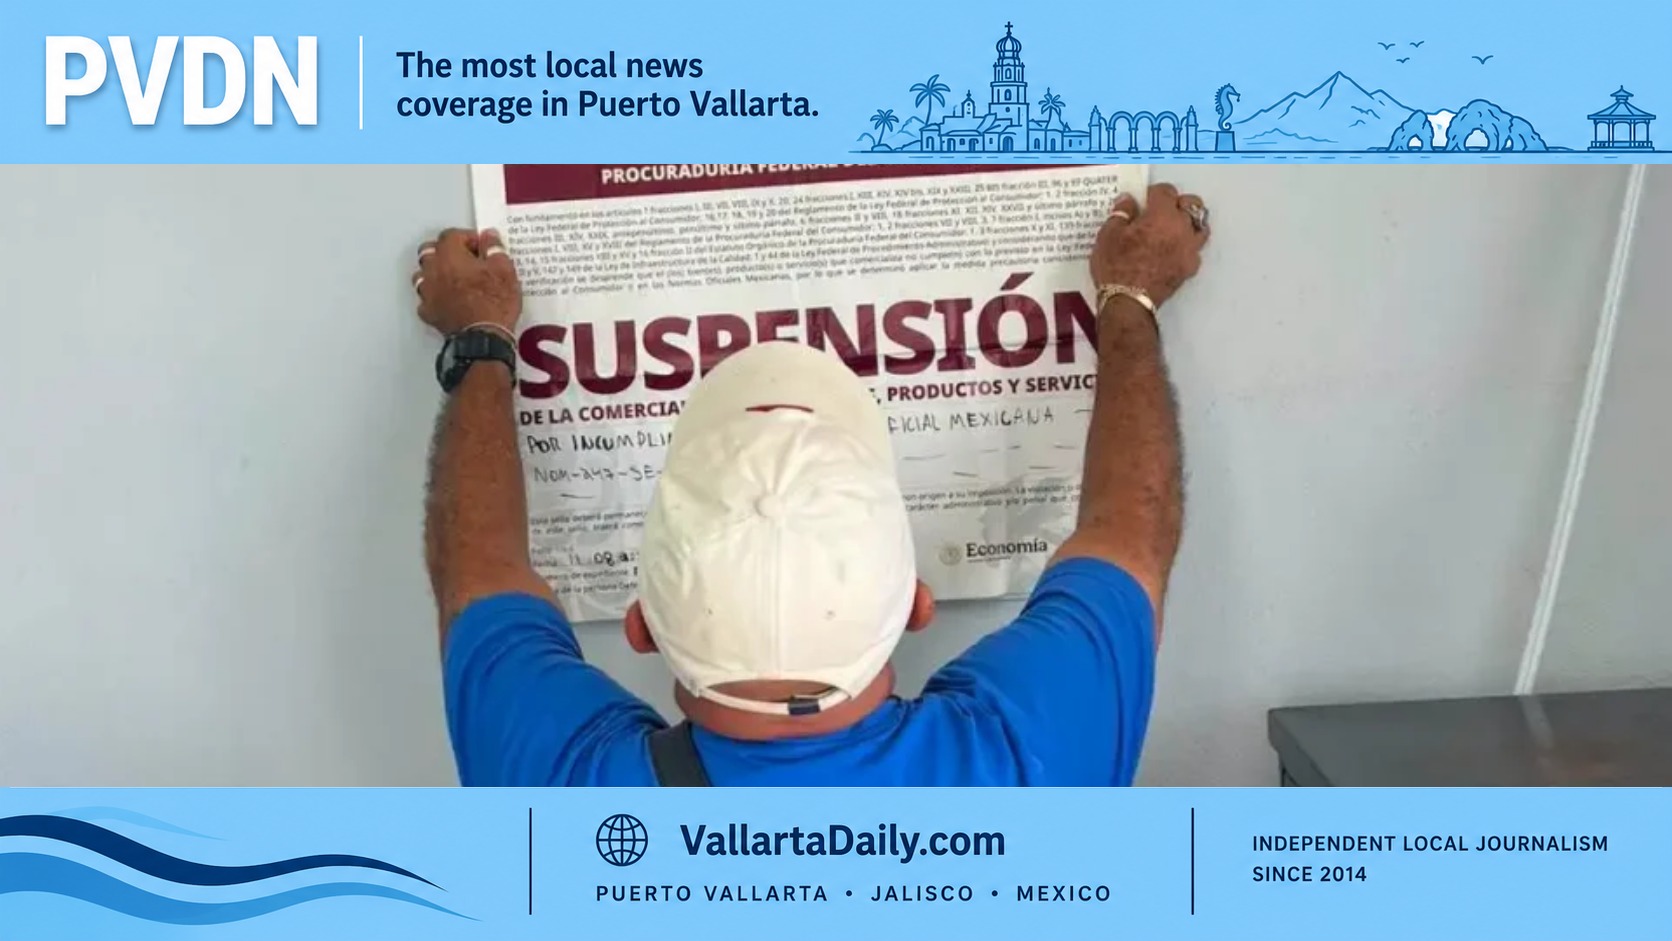
Puerto Vallarta has its own record of confidence problems around development and enforcement. Previous local coverage has followed pre-sale deals leaving buyers in limbo after authorities stopped some projects, and Profeco halted sales at a Tondoroque housing development this year after contract and pricing gaps that could affect buyer certainty. Those cases are different from Proyectos 9, but they point to the same pressure point. Buyers sign before the risk is visible.
The federal rules reviewed here require disclosure, registration of contracts, warranties, and oversight by Profeco. They do not show a blanket requirement that all pre-sale deposits be insured. The stronger proposal would add another party before the buyer’s money enters a project, either through an insurer, a bonding company, or another financial mechanism designed to answer when the developer cannot.